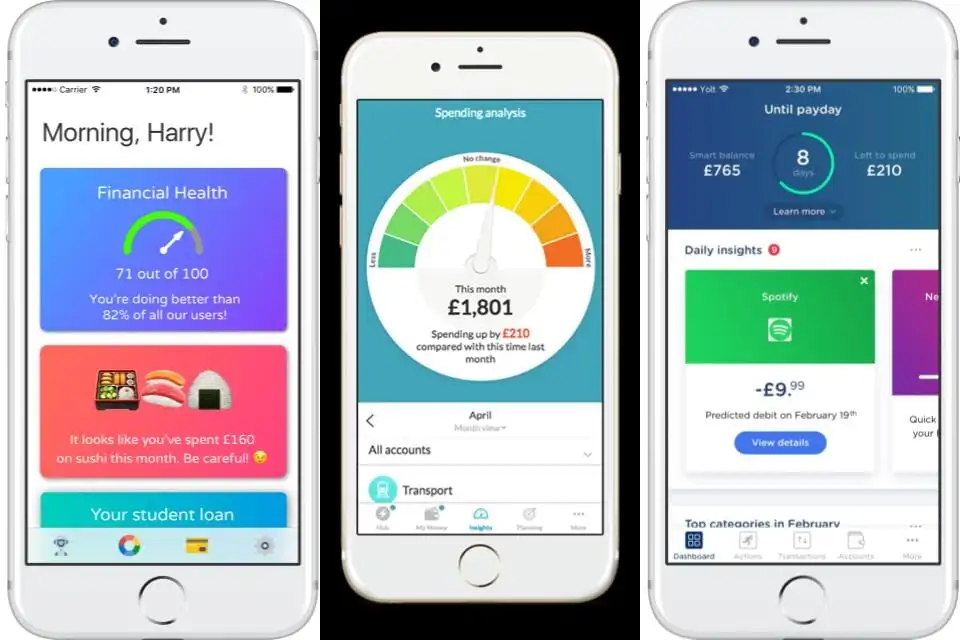
Managing money is easier when you can see where your income goes, plan upcoming expenses, and track progress toward your savings goals. The best budgeting apps help you organize your finances without relying on scattered notes or complicated spreadsheets.
Whether you want to stop overspending, save for an emergency fund, pay off debt, or manage household expenses with a partner, there are budgeting apps designed for different needs and budgets.
In this guide, we compare some of the best budgeting apps, including free options and paid tools. You will learn what each app does, which features matter most, how to choose the right one, and how to create a simple monthly budget.
Best budgeting apps at a glance
| App | Best for | Free option | Main feature |
|---|---|---|---|
| YNAB | Planning every dollar | Free trial | Zero-based budgeting |
| Rocket Money | Recurring expenses and subscriptions | Yes, with limitations | Spending insights and subscription tools |
| Monarch Money | Households and couples | Free trial | Shared budgets and financial tracking |
| Goodbudget | Envelope budgeting | Yes | Assigning money to categories |
| EveryDollar | Simple monthly budgets | Yes | Zero-based planning |
| PocketGuard | Knowing how much is available to spend | Limited option or trial, depending on current offer | Cash-flow and spending overview |
| Empower Personal Dashboard | Tracking spending and investments | Yes | Net worth and financial overview |
| Spendee | Visual expense tracking | Yes, with limitations | Budgets and shared wallets |
Features, account integrations, and prices can vary by country, device, and subscription plan. Before connecting a bank account or paying for a subscription, verify the latest details on the app’s official website.
1. YNAB: Best for planning every dollar
You Need A Budget (YNAB)
YNAB is designed for people who want to decide in advance how their money will be used. Its zero-based budgeting approach encourages you to assign available money to specific priorities, such as rent, groceries, debt payments, savings, and entertainment.
Key features
- Budget categories and spending targets.
- Expense tracking and account imports where supported.
- Savings goals and debt repayment tools.
- Options for sharing a budget with other household members.
- Reports that help you understand spending habits.
Pros
- Encourages intentional spending instead of simply reviewing past transactions.
- Useful for people working toward debt reduction or savings goals.
- Offers educational resources for learning its budgeting method.
Cons
- Requires regular participation and a learning period.
- It is a paid subscription after the trial.
- Automatic bank imports do not support every country or financial institution.
Pricing: The official pricing page lists plans at $14.99 per month or $109 per year in USD, plus applicable taxes. Check the current offer before subscribing.
Best for: People who want a structured approach to managing income, paying bills, and reaching financial goals.
Explore YNAB2. Rocket Money: Best for tracking subscriptions and recurring bills
Rocket Money
Rocket Money combines spending tracking with tools that help users identify recurring charges and manage subscriptions. It can be useful if you have several streaming services, memberships, app subscriptions, and monthly bills.
Key features
- Expense categorization and spending summaries.
- Recurring payment and subscription tracking.
- Budgeting tools and financial insights.
- Additional premium features, which may vary by plan.
Pros
- Can help identify subscriptions you no longer use.
- Useful for reviewing recurring expenses in one place.
- Offers a free starting option in its supported market.
Cons
- Some features require a paid subscription.
- Availability and bank connections may be limited by geography.
- Some bill-negotiation services and other features may have separate conditions or costs.
Pricing: A free tier is available, with premium pricing and features subject to change. Confirm current pricing on the official website.
Best for: People who suspect they are spending too much on subscriptions or want a clearer picture of recurring payments.
Explore Rocket Money3. Monarch Money: Best for couples and household budgets
Monarch Money
Monarch Money provides a broader view of personal and household finances. It combines budgeting with account tracking, financial goals, spending reports, and net worth monitoring.
Key features
- Custom spending categories and flexible budgeting.
- Tracking of supported bank accounts, credit cards, loans, and investments.
- Shared financial planning for couples or households.
- Savings goals, recurring transactions, and reports.
- A dashboard for viewing multiple aspects of your finances.
Pros
- Useful for organizing finances across several accounts.
- Helps households review expenses and savings goals together.
- Offers more comprehensive financial tracking than a simple expense log.
Cons
- It is a paid product after the trial.
- Its many features may feel excessive if you only need a basic budget.
- Account connectivity depends on supported institutions and regions.
Pricing: Recent published pricing lists the Core plan at $14.99 per month or $99.99 per year in USD. Verify the latest plans and trial conditions before subscribing.
Best for: Couples, families, and individuals who want a centralized view of household income, expenses, savings, and investments.
Explore Monarch Money4. Goodbudget: Best free app for envelope budgeting
Goodbudget
Goodbudget uses the envelope budgeting method. Instead of treating your entire bank balance as money available to spend, you divide it into categories such as groceries, transport, housing, entertainment, and savings.
For example, you might allocate $250 to groceries for the month. Every grocery purchase reduces the amount remaining in that envelope, helping you see whether you are staying within your limit.
Key features
- Digital envelopes for spending categories.
- Manual income and expense entry in the free version.
- Budget sharing across supported devices.
- Debt tracking and educational resources.
Pros
- Free access to basic envelope budgeting.
- Works for people who prefer manual tracking.
- Encourages clear limits for discretionary spending.
Cons
- Manual entry takes time.
- The free plan has limits on envelopes and devices.
- Some advanced features require a paid plan.
Pricing: A free version is available. Premium subscription prices and features should be confirmed on the official website.
Best for: Beginners who want to control spending by category without depending on automatic bank connections.
Explore Goodbudget5. EveryDollar: Best for simple monthly budgets
EveryDollar
EveryDollar follows a zero-based budgeting approach. You create a plan for your income, assign amounts to expenses and savings, and adjust categories as your financial priorities change.
Key features
- Monthly income and expense planning.
- Spending categories and savings targets.
- Debt repayment planning.
- Additional features on paid plans.
Pros
- Clear, straightforward budget structure.
- Suitable for people who want to plan before spending.
- Offers a free version with manual entry.
Cons
- Manual tracking may be inconvenient for some users.
- Some automation and additional features require payment.
- Bank connection availability depends on plan and region.
Pricing: A free version is available, with additional tools on paid plans. Confirm the current subscription price on the official site.
Best for: People who want to create a monthly plan and keep their spending aligned with their priorities.
Explore EveryDollar6. PocketGuard: Best for knowing how much you can spend
PocketGuard
PocketGuard focuses on giving users a clearer view of their cash flow. Depending on the features available to your account, it can help you account for income, bills, savings goals, debt payments, and everyday expenses.
Key features
- Spending categories and budget limits.
- Recurring bill and subscription tracking.
- Savings goals and debt payoff tools.
- Account aggregation where supported.
Pros
- Helps users understand upcoming commitments and available spending money.
- Combines several budgeting tools in one interface.
- Offers customizable budget categories.
Cons
- Many advanced features require a subscription.
- Bank connectivity is focused on supported markets, including the US and Canada.
- It may be more than you need if a spreadsheet or simple expense tracker is sufficient.
Pricing: The official pricing page lists a Premium plan at $12.99 per month or $74.99 per year, with other offers potentially available. Check the latest details before subscribing.
Best for: People who want an overview of bills, planned spending, and the amount left for everyday purchases.
Explore PocketGuard7. Empower Personal Dashboard: Best for tracking net worth
Empower Personal Dashboard
Empower is primarily known for its wealth and investment tracking tools, but its dashboard can also help users review spending and monitor their overall financial position.
Key features
- Tracking supported financial accounts.
- Net worth and investment portfolio views.
- Spending summaries and transaction categories.
- Financial planning tools.
Pros
- Useful for viewing spending alongside assets and investments.
- Offers a free dashboard for eligible users.
- Can help users understand how debts and assets affect net worth.
Cons
- It is not primarily a hands-on budgeting app.
- Its investment features may be unnecessary for someone who only wants to track everyday expenses.
- Product availability and account integration vary.
Pricing: The personal dashboard is offered free of charge, although other financial products or services may have separate terms.
Best for: People who want to monitor spending, investments, and net worth in one place.
Explore Empower8. Spendee: Best for visual expense tracking
Spendee
Spendee is a personal finance app designed to help users organize expenses and visualize their money habits. Its budgeting features can help you see how much you spend in different categories and track progress toward spending limits.
Key features
- Expense categories and budget tracking.
- Visual spending reports.
- Shared wallets for managing selected expenses together.
- Bank synchronization or additional features where supported by the plan and region.
Pros
- Visual summaries can make spending patterns easier to understand.
- Useful for organizing different budgets and spending categories.
- Can suit users who prefer a mobile-first experience.
Cons
- Some features require a paid plan.
- Bank connections and supported currencies or institutions may vary.
- Users who want detailed financial planning may prefer a more comprehensive tool.
Pricing: A limited free option and paid plans may be available. Check the current plan details in your region.
Best for: People who prefer visual reports and a straightforward way to monitor spending habits.
Explore SpendeeFree vs. paid budgeting apps: which should you choose?
A paid subscription is not automatically better. The right choice depends on how much help you need, how often you review your finances, and whether the app’s features save you enough time or money to justify the cost.
| Feature | Free budgeting app | Paid budgeting app |
|---|---|---|
| Manual expense tracking | Often available | Usually available |
| Budget categories | Basic or limited categories may be included | Often offers more customization |
| Automatic bank syncing | May be unavailable or limited | Often included where supported |
| Reports and financial insights | Basic reports may be available | May include more detailed analysis |
| Household sharing | May have limits | May include additional users or collaboration tools |
| Customer support | Can be limited | May include expanded support |
Start with a free option if your main goal is to learn where your money goes. Consider paying only after identifying a specific limitation that a premium plan would solve.
How to choose the best budgeting app for your needs
1. Decide what you want to improve
Are you overspending on food, forgetting bills, struggling to save, paying down debt, or trying to manage a household budget? Choose an app that directly supports your main goal instead of selecting one simply because it has the most features.
2. Check whether your bank is supported
Automatic bank synchronization can save time, but availability differs by institution and country. If your bank is not supported, look for manual entry, CSV import, or another method that works for you.
3. Compare the total cost
Review monthly and annual subscriptions, renewal prices, optional add-ons, payment processing, and cancellation terms. An app should support your financial goals rather than become another recurring expense you forget about.
4. Consider privacy and security
Budgeting apps may handle sensitive information about your transactions, income, and financial accounts. Read the privacy policy, understand what information is collected, and check how account connections work. Use a strong unique password and multi-factor authentication where available.
5. Pick a method you will actually use
Some people like manual tracking because it makes them pay attention to every purchase. Others prefer automation. A simple app that you review consistently can be more useful than an advanced app you stop opening after a week.
How to create a monthly budget using an app
Once you have chosen an app, follow these steps to build a budget you can maintain.
- Calculate your take-home income. Use the amount you expect to receive after deductions, rather than gross salary.
- List fixed expenses. Include rent or mortgage payments, insurance, subscriptions, and other regular bills.
- Estimate variable expenses. Review groceries, transport, utilities, dining out, and other flexible categories.
- Set savings targets. Decide how much to put toward emergencies, upcoming purchases, and long-term goals.
- Plan debt payments. Include minimum payments and any additional amount you can reasonably afford.
- Track transactions. Categorize purchases and correct any inaccurate automatic classifications.
- Review weekly. Adjust your spending plan when actual expenses differ from your estimates.
Try the 50/30/20 budget calculator
The 50/30/20 rule is a popular budgeting framework. It divides after-tax income into three broad groups: 50% for needs, 30% for wants, and 20% for savings and debt repayment. It is a starting point rather than a strict rule; your actual needs, cost of living, and financial goals may require different percentages.
Calculate your monthly budget
Enter your monthly take-home income to estimate how much you could allocate to each category.
Needs: $1,500
Wants: $900
Savings and debt repayment: $600
This calculator uses the 50/30/20 framework. It is an educational example, not personalized financial advice.
Best budgeting apps for users outside the United States
Not every budgeting app offers the same features internationally. Some rely on connections to US or Canadian financial institutions, while others allow manual entry or file imports.
If you live in Peru or another country where automatic bank connections may be limited, check the following before choosing an app:
- Bank compatibility: Verify that your bank and account type are supported in your country.
- Currency support: Confirm that the app can display your preferred currency and handle your budgeting needs. Multi-currency support does not always mean that multiple currencies can be combined in one budget.
- Manual transactions: Look for a way to record cash purchases and expenses that do not appear in a connected account.
- Data import: CSV or spreadsheet imports may be useful if automatic connections are unavailable.
- Local payment options: Confirm that you can pay for a subscription and cancel it using a method available to you.
- Privacy and local requirements: Read how the provider handles personal and financial data.
If you only need to record income and expenses in soles, a spreadsheet or manual budgeting app may be enough. You do not necessarily need to give a third-party service access to your financial accounts.
Common budgeting mistakes to avoid
- Creating an unrealistic budget: Use actual spending history to estimate categories instead of choosing arbitrary amounts.
- Forgetting irregular expenses: Plan for annual fees, vehicle maintenance, medical costs, gifts, and other expenses that do not occur every month.
- Ignoring cash purchases: Record cash spending so your budget reflects what you actually spend.
- Tracking expenses without making a plan: Review the information and decide what needs to change.
- Giving up after one difficult month: Treat unexpected expenses as information and revise your plan when needed.
- Paying for unnecessary features: Start with the simplest tool that meets your needs.
- Connecting accounts without checking privacy: Understand what information you are sharing and how to disconnect accounts if you stop using the service.
Frequently asked questions
What is the best budgeting app overall?
There is no single best app for everyone. YNAB is a strong option for people who want structured, hands-on budgeting. Rocket Money may suit people focused on subscriptions and recurring expenses, while Monarch Money is designed for broader household financial tracking.
What is the best free budgeting app?
Goodbudget offers a free envelope-budgeting option, EveryDollar has a free manual budgeting version, and Empower offers a free personal finance dashboard. The best choice depends on whether you want to plan spending, track expenses, or monitor investments and net worth.
Are budgeting apps safe to use?
Security practices vary by provider. Review the privacy policy and account connection method, enable available security features, and avoid sharing banking passwords directly unless the provider's official connection process explicitly requires it and you understand the implications. Never share verification codes with someone who contacts you unexpectedly.
Can I use a budgeting app without linking my bank account?
Yes. Apps such as Goodbudget allow manual tracking, and a spreadsheet can also work. Manual entry takes more effort but can provide greater control over which financial information you share with third-party services.
Do budgeting apps work in Peru?
Some apps can be used internationally, but automatic bank synchronization and premium features may be limited. Before registering, confirm that the app supports your country, preferred currency, payment method, and financial institution. Manual expense tracking is an alternative if bank connections are unavailable.
What is the difference between an expense tracker and a budgeting app?
An expense tracker primarily records where your money went. A budgeting app also helps you decide where your money should go by setting spending limits, allocating income, planning bills, or monitoring savings goals. Some apps do both.
Is it worth paying for a budgeting app?
A paid app may be worthwhile if its features help you manage finances more consistently, save time, or identify avoidable expenses. Start with a free option if you are unsure, then consider upgrading only when you have a specific need that justifies the cost.
How often should I check my budget?
A weekly review is a practical starting point for many people. Check upcoming bills, compare actual spending with your plan, correct transaction categories, and adjust amounts when necessary. A short, consistent review can be more useful than an occasional lengthy session.
Final thoughts
The best budgeting app is the one that helps you make better decisions about your money and that you will continue using. You may prefer the structured planning of YNAB, the envelope method in Goodbudget, the subscription tools in Rocket Money, or the household overview offered by Monarch Money.
Start by identifying your main financial goal, compare free and paid options, and check whether the app supports your country and bank. Then set realistic spending limits, track your expenses, and review your progress regularly.
You do not need a complicated system to improve your finances. A clear plan, consistent tracking, and small adjustments over time can help you build better money habits.